7 November 2026 | Curated by Gurdeep Singh, Amritsar, Punjab
Kotak Mahindra Bank reported higher profit and net interest income for the July–September quarter of FY2026–27, supported by loan growth, stronger fee income and improving credit costs. The results also show a key trade-off for the lender: substantial foreign-currency deposit mobilisation supported funding, but contributed to moderation in its net interest margin.
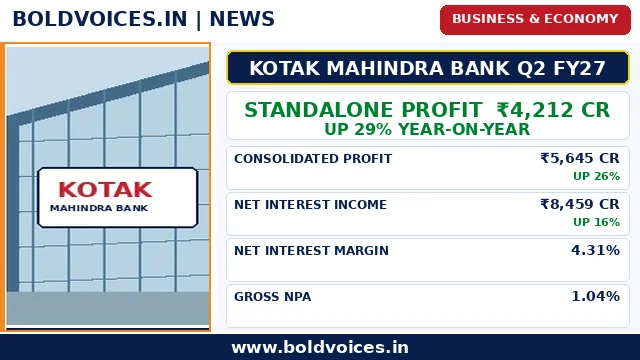
For Q2 FY27, the bank reported standalone profit after tax (PAT) of ₹4,212 crore, up 29% year-on-year. Consolidated PAT rose 26% to ₹5,645 crore. Standalone net interest income (NII) increased 16% to ₹8,459 crore, while net interest margin (NIM) stood at 4.31%.
Standalone and consolidated profit both increase
The standalone result reflects the bank’s own operations. Its PAT increased from ₹3,253 crore in Q2 FY26 to ₹4,212 crore in Q2 FY27, a 29% annual rise. It was also 2% higher than the ₹4,123 crore recorded in Q1 FY27.
At the consolidated level, which includes the wider group, PAT reached ₹5,645 crore, compared with ₹4,468 crore a year earlier. The year-on-year increase was 26%, while the quarter-on-quarter rise was 3%.
Keeping these two measures separate is important. Standalone numbers help assess the bank itself, while consolidated results include the contribution of subsidiaries and other group entities.
Net interest income rises 16%, while NIM moderates
Standalone NII increased to ₹8,459 crore from ₹7,311 crore in Q2 FY26. The 16% year-on-year rise indicates stronger core interest earnings, with a 7% increase compared with the previous quarter.
However, NIM was 4.31%, compared with 4.54% in Q2 FY26 and 4.53% in Q1 FY27. The bank attributed much of this moderation to the mobilisation of FCNR(B) deposits during the quarter. Its cost of funds was 4.52%, compared with 4.70% a year earlier and 4.46% in the preceding quarter.
FCNR(B) deposits are foreign-currency non-resident bank deposits. They can help diversify a bank’s funding base, but their pricing and related lending or hedging arrangements can affect reported margins. Investors should therefore examine both deposit mobilisation and the cost at which the bank raises funds.
Fee income and operating performance strengthen
Fees and services income rose 21% year-on-year to ₹2,926 crore, from ₹2,415 crore. The increase reflects the contribution of non-interest services such as transaction-related fees and other banking services.
The bank reported that operating profit increased 21% year-on-year. Cost to assets improved to 2.40%, while the annualised credit cost was 0.35%. These measures help investors assess the efficiency of operations and the cost of potential loan losses.
Asset quality remains a key strength
Kotak Mahindra Bank reported a gross non-performing asset (GNPA) ratio of 1.04% and a net NPA ratio of 0.24%. Slippages during the quarter declined to ₹1,230 crore, down 24% from ₹1,629 crore in Q2 FY26.
Lower slippages and contained NPA ratios are constructive indicators, but they need to be assessed alongside loan growth, recoveries, write-offs and provisioning. Rapid expansion can change the risk profile of a loan book over time, so credit quality will remain an important measure in subsequent quarters.
Customer assets and capital position
Consolidated customer assets stood at ₹6,99,250 crore, up 21% year-on-year. The group’s customer assets include advances and specified credit substitutes. Consolidated customer assets under management were ₹8,14,118 crore, while net worth stood at ₹1,94,706 crore.
The consolidated capital adequacy ratio was 22.4%, with the common equity tier 1 ratio at 22.1%. These capital measures indicate the buffer available to support lending and absorb potential losses, subject to applicable regulatory requirements and risk-weighted asset changes.
International deposits and funding strategy
During the quarter, Kotak mobilised approximately ₹55,344 crore in FCNR(B) deposits. It also provided around ₹16,110 crore in loans through its international branches. The bank’s disclosures indicate that the funding mobilisation was a significant part of the quarter’s balance-sheet activity.
The longer-term impact will depend on the stability and cost of these deposits, the deployment of funds and the bank’s ability to manage currency and liquidity risks. Strong deposit inflows can support growth, but the price of funding matters just as much as the amount raised.
What should investors watch next?
NIM recovery: Whether margins stabilise as the effect of FCNR(B) mobilisation changes.
Deposit costs: Whether the bank can maintain deposit growth without a sustained increase in funding costs.
Loan quality: Whether lower slippages and contained NPAs continue as advances expand.
Fee income: Whether non-interest revenue maintains its strong growth.
Capital and returns: Whether capital adequacy and return ratios remain healthy as the group grows.
The bigger picture
Kotak Mahindra Bank’s Q2 FY27 results show healthy annual profit growth, a 16% rise in standalone NII, higher fee income and contained asset-quality indicators. Consolidated profit also increased, and the group retained a strong capital position.
The key issue to monitor is the balance between growth and margins. FCNR(B) deposit mobilisation supported funding, but NIM moderated to 4.31%. The bank’s ability to manage funding costs, sustain loan growth and preserve credit quality will help determine whether the current earnings momentum can continue.
This article is for news and general information only. It is not investment advice or a recommendation to buy or sell any security. Readers should consult official company disclosures and consider their own financial circumstances before making investment decisions.
Like what you read? Help BoldVoices.in keep independent journalism going.
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.