7 November 2026 | Curated by Gurdeep Singh, Amritsar, Punjab
Axis Bank reported a 38% year-on-year increase in profit after tax for the July–September quarter of FY2026–27, supported by higher net interest income, strong loan growth and an improvement in asset quality. The private-sector lender’s results also showed continued expansion in deposits and advances, although quarterly profit was slightly lower than in the preceding three months.
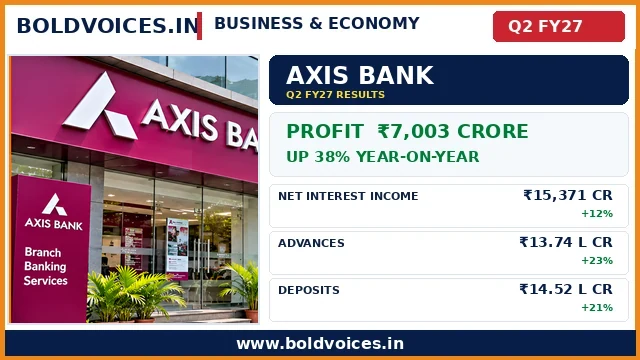
The bank reported profit after tax of ₹7,003 crore for Q2 FY27, compared with ₹5,090 crore a year earlier. Net interest income (NII) increased 12% to ₹15,371 crore. Advances grew 23% year-on-year to ₹13.74 lakh crore, while total deposits rose 21% to ₹14.52 lakh crore.
Profit rises 38%, but slips slightly quarter-on-quarter
Axis Bank’s Q2 FY27 profit after tax increased from ₹5,090 crore in the corresponding quarter last year to ₹7,003 crore. However, it was 2% lower than the ₹7,114 crore recorded in Q1 FY27.
The year-on-year comparison therefore shows strong annual growth, while the sequential movement indicates that earnings did not increase every quarter. Investors should consider both comparisons when evaluating the bank’s performance.
Net interest income grows 12%
Net interest income—the difference between interest earned on loans and investments and interest paid on deposits and borrowings—rose 12% year-on-year and 5% quarter-on-quarter to ₹15,371 crore.
Net interest margin (NIM), a measure of the spread earned on interest-bearing assets, stood at 3.36%. Excluding the impact associated with FCNR(B) deposits, the bank reported NIM of 3.47%. NIM is important because deposit pricing, loan yields, product mix and liquidity conditions can all influence a bank’s core earnings.
Core operating revenue reached ₹21,817 crore, up 10% year-on-year. Fee income increased 6% to ₹6,381 crore, with granular fees accounting for 90% of total fee income. Core operating profit was ₹10,998 crore, up 11% from the year-ago quarter.
Advances and deposits continue to expand
Axis Bank’s balance sheet reflected strong lending and deposit growth as of 30 September 2026:
Metric
Q2 FY27
Year-on-year growth
Net advances
₹13.74 lakh crore
23%
Total deposits
₹14.52 lakh crore
21%
Total assets
₹20.46 lakh crore
22%
Shareholders’ funds
₹2.19 lakh crore
15%
Retail loans grew 16% year-on-year, while the bank’s focus segments—including small-business banking, small and medium enterprises, mid-corporate, rural and selected retail lending categories—recorded growth of 18%. The small-business banking, SME and mid-corporate portfolio together reached ₹3.316 lakh crore.
Deposit growth remains equally important. A bank needs stable funding to support loan expansion, and competition for deposits can influence the cost of funds and future margins. Axis Bank reported strong growth across term deposits and savings balances, alongside inflows through FCNR(B) deposits.
Asset quality improves
The bank reported a gross non-performing asset (GNPA) ratio of 1.16%, compared with 1.46% a year earlier. The net NPA ratio stood at 0.35%, against 0.44% in the year-ago period.
Lower NPA ratios generally indicate an improvement in the proportion of loans classified as stressed or non-performing. Axis Bank also reported a net credit cost of 0.45%, down 28 basis points year-on-year and 18 basis points sequentially.
Asset quality remains a critical measure for lenders because rapid loan growth is sustainable only when underwriting standards, collections and risk controls remain effective. Investors should continue to monitor fresh slippages, recoveries, provisioning and the performance of unsecured lending portfolios.
Operating efficiency and capital position
Axis Bank reported a cost-to-assets ratio of 2.14%, down 24 basis points year-on-year and six basis points quarter-on-quarter. The bank’s capital adequacy ratio under Basel III stood at 16.27%, with Tier I capital at 14.96%.
These indicators help assess the bank’s ability to absorb losses, fund expansion and manage operating costs. Capital strength is particularly relevant when advances are growing at a double-digit pace.
What should investors watch next?
Net interest margin: Whether NIM remains stable as deposit competition and loan pricing evolve.
Deposit mobilisation: Whether deposit growth keeps pace with advances without materially increasing funding costs.
Asset quality: Whether lower GNPA and net NPA ratios are sustained as the loan book expands.
Credit growth: Whether retail, SME and corporate lending maintain momentum without weakening underwriting standards.
Operating costs: Whether technology, branch expansion and employee expenses remain under control.
Capital adequacy: Whether the bank retains a comfortable capital buffer as its balance sheet grows.
The bigger picture
Axis Bank’s Q2 FY27 results combine strong annual profit growth, higher net interest income, 23% advances growth and improving asset-quality ratios. The bank’s deposit base also expanded, supporting its ability to fund further lending.
The quarter was not uniformly stronger across every comparison: profit declined 2% sequentially and NIM stood at 3.36%. The next phase will depend on balancing loan growth with deposit mobilisation, preserving margins and maintaining credit quality. For India’s banking sector, Axis Bank’s results highlight the continuing importance of funding discipline and prudent risk management alongside headline growth.
This article is for news and general information only. It is not investment advice or a recommendation to buy or sell any security. Readers should review the bank’s official disclosures and consider their own financial circumstances before making investment decisions.
Like what you read? Help BoldVoices.in keep independent journalism going.
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional
Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.